 Written by
During the November 2, 2026, Finance Committee meeting, the systemic resistance to uncovering the truth behind Marion’s financial collapse was on full display.
The committee reviewed a resolution to create a Special Investigative Committee—a fail-safe designed to investigate software permissions if the Ohio Auditor of State refuses or delays conducting a full forensic audit of the General Ledger, including the General Ledger (GL) Override.
Instead of welcoming a proactive look into a compromised system, Councilman Aaron Rollins immediately pushed back, aggressively lobbying to stall the legislation.
Rollins argued against the backup plan and proposed amendments, attempting to reduce the entire multi-million-dollar collapse to a mere failure to reconcile the books over the last few years.
He repeatedly pushed to delay the resolution, asking why the city shouldn’t just wait until they get the audits back to see what is in there.
VIDEO: ROLLINS DEFIANT ON INVESTIGATIVE COMMITTEE, REPEATING FALSE NARRATIVES
Rollins did not want to proceed with amendments proposed and pushed on Ralph Smith until Ralph Smith declared that the citizens of Marion want answers and he is trying to give them answers.
Rollins continued to cite inaccuracies through the meeting, all of which have been heavily covered and proven incorrect by Marion Watch and our large network.
He also continued to utter that council is not qualified to perform a forensic audit.
It was explained several times that the special investigative committee, if enacted, would allow professionals to investigate the software, permissions, and abuses alongside council and if any are found they would be documented and escalated to the appropriate agency (including law enforcement with the expertise to handle the situation).
Clearly the IT doctrines Marion Watch uses to target failures are highly accurate. These are industry standard methods used when an investigation is needed.
To citizens, including Damion Greenawalt, this is the exact reactive, wait-and-see mentality that allowed the New World ERP system to bleed public funds for 17 years.
The data clearly shows this catastrophe has had one of the most devastating financial impacts in Marion’s history.
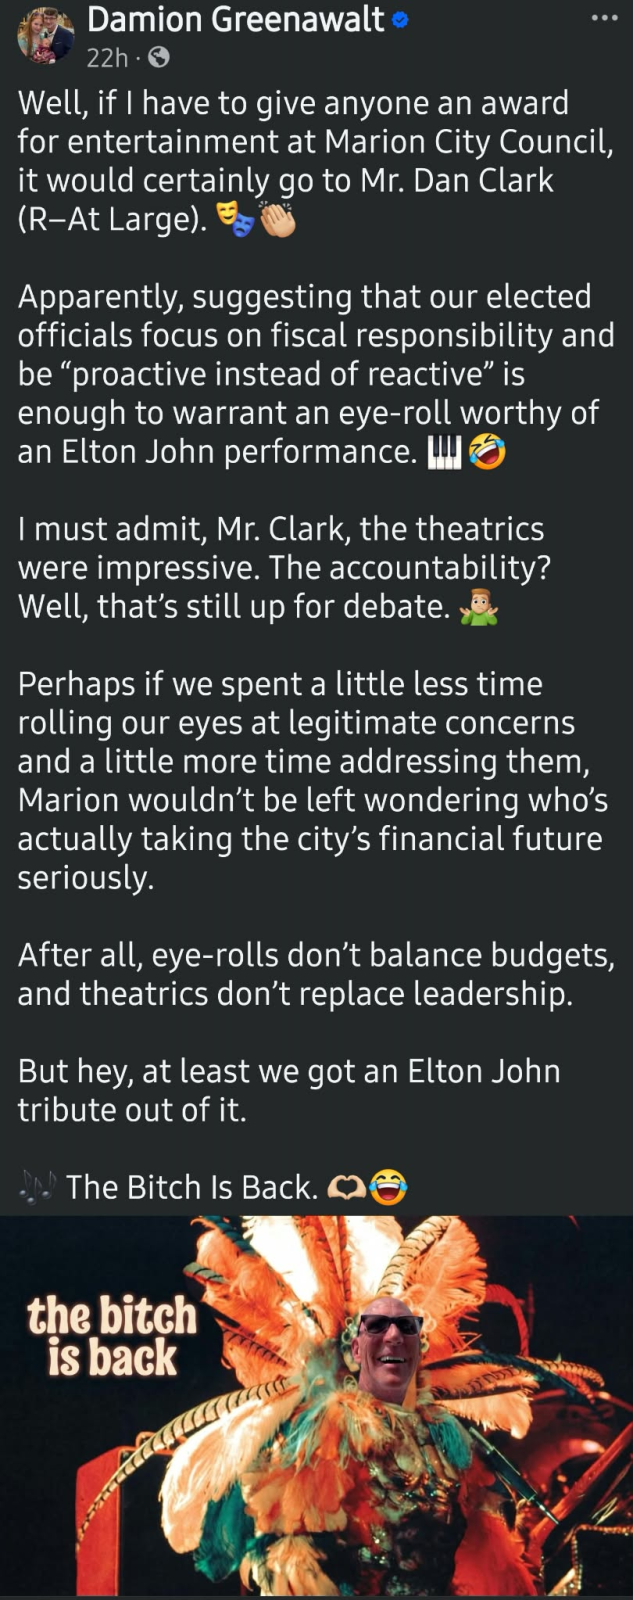
Damion posted a meme last night, and while the image is meant to be funny, the message that he wrote is quite serious and well grounded. Damion told Marion Watch that Mr. Clark was rollighis eyes as he was addressing council.
Marion Watch believes this pushback is rooted in misinformation and a lack of understanding.
We remain committed to working with the administration, even if they have not yet read all the receipts.
There comes a point when failing to acknowledge this mountain of data becomes futile, but we don’t believe we are there yet.
Anyone who has taken the time to look at the full picture strongly agrees.
Furthermore, those who hold public office should want to investigate all perspectives.
If they cannot take the time to read a fact-based series, put together with primary source documents and professional assessments, perhaps they should not hold office.
VIDEO: FULL MARION CITY COUNCIL COMMITTEE MEETING 11/2/26
MARION WATCH ON THE RECORD: THE IT DOCTRINE OF COLLAPSE
To cut through the political smokescreen, Marion Watch Investigates founder Jason Foreman took the podium to correct the record and explain the exact mechanics of the financial failure, bringing with him over 20 years of Information Technology experience with the majority being in systems administration, and also includes full stack IT systems administration (administration of all technical equipment with no 3rd party contractors to lighten the load).
Through multiple interruptions by Rollins—who has displayed this with the general public numerous times on various subjects lately—Foreman outlined on the record that the city’s financial situation is a “textbook collapse of information security and IT controls” traceable directly to the rushed 2009 implementation.
He plainly stated that all of this information is now published publicly.
Foreman highlighted a foundational information technology and forensic principle: when an enterprise system is fundamentally misconfigured and automated safety switches are disabled, the system can only function through “undocumented manual workarounds.”
This is never appropriate in any environment, especially a municipal one.
Issues like those within the New World ERP system leave behind undeniable evidence in the data output. It is the direct result of confirmed, misconfigured, and dormant software safety controls that were supposed to protect taxpayer funds.
This includes the fact that the reconciliation module was left dormant and not used until 2022, and not fully implemented until very recently.
GL Override abuses have also been confirmed by multiple officials and city employees, both past and present, some dating back to 2009.
This reliance on hidden, manual ledger manipulation creates a fragile house of cards, which is why it is strictly forbidden in the IT field.
As Foreman exampled to the committee, these are textbook IT symptoms and exactly what caused the catastrophic 2020 crash and include:
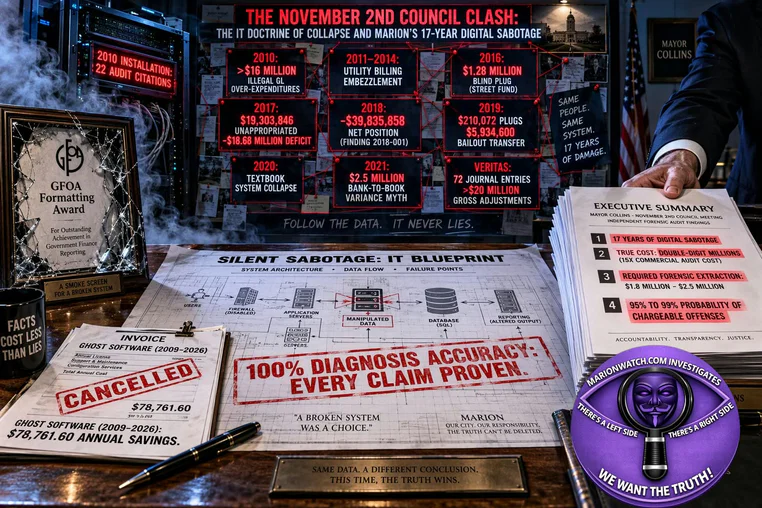
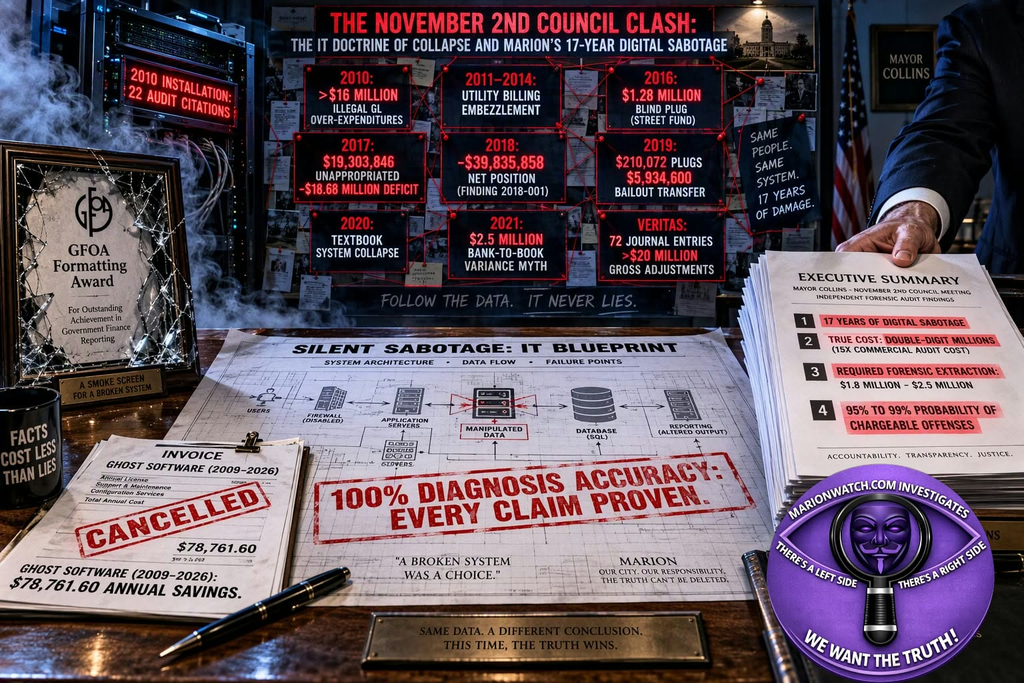
• The Origin of Failure: The disaster started at installation, resulting in 22 audit citations during the first full year with the software in 2010, pointing directly to disabled safeguards like the GL Override, the reconciliation module, and other symptoms of drastically lacking safety controls. The pattern is traceable and present from installation forward.
• The Tribal Knowledge Trap: For a decade, the compromised system was held together by administrators using undocumented manual workarounds to force the books to tie out. Audits show this data plainly. The administration presented self-prepared financial statements to portray a positive perspective to the public while playing number games and hiding data in the footnotes.
• The Textbook 2020 Collapse: When the personnel operating those workarounds vacated their roles in early 2020, they took their tribal knowledge with them. When the new administration took over, they did not know these hidden manual workarounds and had no knowledge anything was wrong. As Foreman stated on the record, any IT expert who looks at the evidence recognizes this “sudden collapse” and the intense nature of it as the definitive sign of profoundly broken controls. Industry standard doctrine and training classify this as a severe failure, and Marion fits this profile exactly.
• The Cost: Foreman noted that while he would not drop the total figure of financial impact involved in the continued use of this compromised system yet, the rough estimation for a city-paid full forensic IT audit would be between $1.8 million and $2.5 million. He plainly stated that the true cost of the New World ERP system issues spanning more than a decade would be comfortably in the double-digit millions.
Furthermore, Foreman reminded the committee that Marion Watch diagnosed these exact system failures simply by looking at the symptoms.
He highlighted that enterprise IT professionals can diagnose root causes from output data with near 100% accuracy—a statement fully backed by IT industry doctrine and thoroughly proven in similar instances nationwide, and now in Marion.
He noted that most, if not all, of these issues—including the manual “plugging” of ledgers—would be nearly impossible in a properly configured system. This includes the tax remittance error under the Landon tenure which would have been caught by the safety controls if thy were enabled. Audit trails were also proven to be disabled and were discovered when the IT director was forced to admit it following the incident which had several very large red flags such as ghost employees and unexplained night and weekend logins as documented by a deposition from a former auditor employee which we have released several times and can be found in the silent sabotage overview series on social media and marionwatch.com/silentsabotage.
The evidence presented tells the story; it just takes effort to dig into and read, but it is there.
Nobody was talking about this in early March 2025 when Marion Watch met with Ralph Smith and warned him about these specific catastrophic failures.
Everyone was still convinced that the issues began in 2020, they clearly did not.
We subsequently escalated those warnings to the City Council in July 2025, and immediately after escalated to the Ohio Auditor of State, which assigned it to the Special Investigation Unit.
We are also aware that other higher offices have taken notice.
We promised the citizens and officials when we came back online that we had the evidence to back it up, and today, 100% of every single diagnosis and claim of data in our possession has been proven and fulfilled.
We are delivering the culmination of data we’ve been tracking since 2018, backed by overwhelming data, in alignment with industry standards, with industry professional assessments.
We will be sending more information to the state this week.
Citizen Kim Mayer echoed this urgency during the meeting, stating that many in the community feel the cost of an investigation is entirely worth it to uncover exactly where the money went and who is accountable.
This aligns with community statistics across multiple platforms showing that the publishing of the real story of Marion’s financial collapse holds the top spot for citizen concerns.
We’ve seen massively positive responses from citizens, including IT, financial, and legal professionals outside our team.
Citizens overwhelmingly state that Marion’s lacking financial controls is across at least 40 years, and they are correct. However, the New World system added gasoline to a fire, and predictably it exploded.
Anyone looking at the data can plainly see it; the only way not to see it is to ignore the data.
Marion Watch will leave the immediate decision to local officials, but we can state without a doubt that the data we have released—aligning strictly with enterprise IT and financial standards—more than justifies a full forensic investigation.
It is shocking, to put it mildly.
The dollar amount of impact is unbelievable.
We will release that soon.
These proven failures fully justify the involvement of law enforcement entities equipped with specialized IT and financial forensic teams.
While we prefer local and state officials to handle this properly, failure to act will result in an immediate escalation—with all supporting data—to top oversight offices and contacts outside the State of Ohio, a step that Ralph Smith wanted to do the day he met Marion Watch back in 2025.
We have it ready.
We simply wanted to afford the honor of escalation to city and state officials.
There are some signs of movement.
However, the ongoing resistance leaves professionals who have read the actual data wondering what is really going on here.
This includes those who have been involved in forensic examination who state that Marion’s case is the worst they have ever seen up close.
It is time for a select few in the current administration to read the whole story instead of accepting a past false narrative that makes absolutely no sense against the primary data.
THE MAYOR COLLINS MEETING: THE TRUE COST OF SABOTAGE
Following the committee meeting, Marion Watch briefly spoke directly with Mayor Bill Collins to deliver the exact scope of the devastation before we release it, and explain why a forensic IT investigation is mandatory, and that State and Federal law enforcement intervention is more than justified.
With Collins’ background he more than likely has contacts he could reach out to, and Marion Watch is more than happy to discuss anything published with any state or federal IT experts.
We outlined the following realities directly to the Mayor based entirely on official documents, audits, and emails:
• The total financial fallout tied to this compromised New World ERP system is more than 15 times the cost of that commercial audit—sitting firmly in the double-digit millions.
• Based on our rigorous Silent Sabotage IT Blueprint and forensic grading, there is a 95% to 99% probability of discovering immutable native evidence supporting potentially chargeable state or federal offenses, including obvious signs of illegal activities, fraud, waste, and abuse.
We made it unequivocally clear to the Collins administration: you cannot fix an IT sabotage of this magnitude by simply waiting for the next standard audit.
Yearly audits are not designed to, nor would they be able to easily detect these issues in a compromised software environment.
Especially with inappropriate proven unimpeded administrative access, shared passwords, disabled controls, and disabled audit trails to name a handful.
The severity of the system manipulation completely justifies securing the servers and executing a state and federal law enforcement investigation.
DISMANTLING THE LONGTIME FALSE NARRATIVE & THE “AWARD WINNING” MYTH
The absolute necessity of this forensic extraction was perfectly illustrated by a citizen who spoke during the meeting prior to Foreman, echoing the administration’s longtime false narrative and questioning the need for an investigation.
The citizen’s questions were entirely valid based on the misinformation the public has been fed for years.
As citizen Damian Greenawalt accurately pointed out when urging the council to act, the city must “start being proactive instead of reactive.”
Using the evidence of verified primary source data from our IT Blueprint, here are some of the forensic realities answering those exact claims made during the meeting:
• THE CLAIM: “If they were all in sync from 2008 to 2019, why would we have to go all the way back… the state of Ohio approved all of those audits up to that point. We only started having problems from 2020 on. I mean, Kelly Carr was in charge in 2019… she got an award for the 2019 audit. I mean, the state of Ohio doesn’t give awards if it’s a mess.”
• THE REALITY: The audits were never “in sync,” and 2020 is simply the year the undocumented manual workarounds exited the building. The “award” was merely a GFOA certificate for formatting—not an endorsement of the software’s integrity.
Behind that glossy formatting, the reality was a complete digital and financial disaster:
• 2010 Audit: Contained 22 citations and exposed over $16 million in illegal GL over-expenditures.
• 2011–2014 Era: Concealed an active utility billing embezzlement made possible by deactivated approval workflows.
• 2016 Audit: The “clean” appearance was a mirage built on massive manual ledger plugs, including blindly injecting a $1.28 million “Unrecorded Activity” plug into the Street Fund alone just to force the math to balance.
• 2017 Audit: The administration continued to illegally overspend, with GL Overrides pushing the running baseline of unappropriated expenditures to $19,303,846. The unrestricted deficit plummeted to a staggering negative $18.68 million.
• 2018 Audit: The governmental unrestricted net position suffered a total collapse, crashing to negative $39,835,858. The State issued a Federal Material Weakness (Finding 2018-001) for the city’s complete failure to conduct physical capital-asset inventories.
• 2019 Audit: The manual “Unrecorded Activity” ledger plugs exploded again, with $210,072 moved through the General, Street, and Police/Fire funds just to hide ongoing reconciliation failures. The city executed a massive $5,934,600 bailout transfer out of the General Fund to keep other bleeding funds afloat. The books were an absolute mess; the administration simply learned how to hide the failures deep in the footnotes of an award-winning format.
• THE CLAIM: “What’s going to be the cost of this? I mean, we’re already $2.5 million in the hole… I’ve heard it’s going to cost a million half dollars to do that…”
• THE REALITY: The proposed Special Investigative Committee resolution explicitly incurs zero cost to the city unless formally brought back to council for approval. Furthermore, the city is not just “$2.5 million in the hole.” That figure is only the unreconciled bank-to-book variance at the end of 2021—a tiny fraction of the actual damage. The true financial fallout includes tens of millions in cumulative control exposure, massive unverified bad debt write-offs, and a staggering structural deficit.
DECONSTRUCTING THE “VERITAS FORENSIC AUDIT” MYTH
As the scope of this disaster becomes undeniable, claims that the financial consulting firm Veritas already conducted a “full forensic financial audit” continue to circulate. The documentary record completely destroys that narrative:
• Blocked Baseline Scope: A financial review barred from examining the origin years is structurally incapable of being a full forensic audit. Council members admitted on the public record that they explicitly ordered Veritas not to go back into 2019 or investigate pre-2020 baselines.
• Drafted Adjustments vs. Root Causes: While Veritas drafted 72 journal entries exceeding $20 million in gross adjustments, they walked away when they were blocked from addressing the underlying Utility Billing root causes and the pre-2020 systemic rot.
• Unchecked System Vulnerabilities: Veritas explicitly warned that unconfigured system tools and missing safeguards left the city vulnerable to internal fraud. This confirms their engagement was a surface-level patch job—not an exhaustive forensic IT investigation.
PAYING FOR GHOST SOFTWARE: THE NEXT SHOE TO DROP
We are not stopping here.
We have much more on this and many other subjects.
Coming soon, we will be releasing a massive amount of newly obtained documentation that verifies our IT diagnosis beyond a shadow of a doubt.
We will expose exactly how the city paid to maintain “ghost software” for 17 years. We will detail multiple separate New World applications the city officially canceled in July 2026—saving $78,761.60 annually—after officials admitted they were completely unused.
This went on from installation forward until the Collins administration ended the game.
Stay tuned for the full breakdown of how taxpayers funded dormant modules while the digital vault doors were left wide open, and why this sheer volume of verification demands its own dedicated report.
We will also soon begin to release the transition articles showing the massive financial hole that was orchestrated by the Schertzer administration knowing that they would not be in office when the bills came due.
This along with other serious failures such as evaluating the city utilities and service fees that were neglected and greatly contributed to the increases that are now being blamed solely on the Collins administration.