 Written by
Let us be unequivocally clear from the outset: Marion Watch has been investigating this system since 2018, with documented suspicions dating back to 2016.
Because we know we are looking at a severely compromised environment, we are building a case—not writing stories.
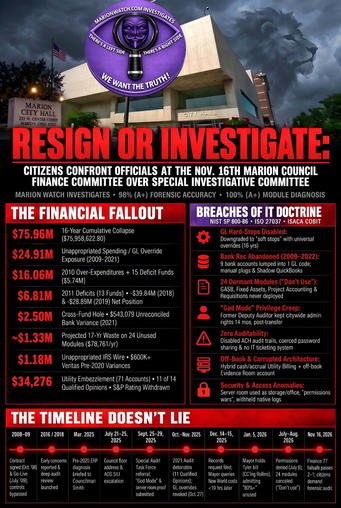
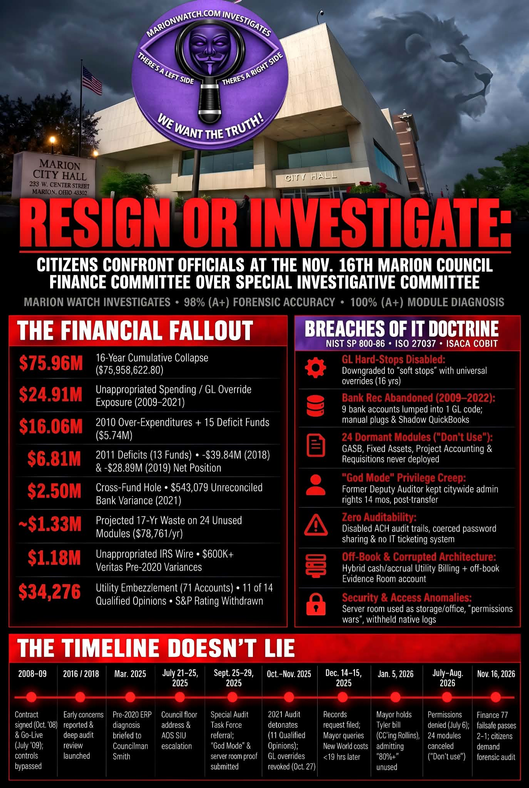
The General Ledger (GL) override abuse that enabled $24,910,081 in illegal, unappropriated spending between 2009 and 2021—cited directly in official State of Ohio audits—is only one symptom of a far deeper institutional catastrophe.
Public records, native system screenshots, vendor contracts, eyewitness statements, official council testimony, State of Ohio audits, and other primary documentation compiled in Marion Watch’s Silent Sabotage investigative series prove that Marion’s $75.9 million financial collapse ($75,958,622.80 in cumulative fallout) was not a sudden accounting glitch, and it certainly did not begin in 2020.
It was a wall-to-wall collapse of enterprise Information Technology (IT) governance, oversight, and leadership—masked by undocumented manual workarounds and off-book financial plugs that sit in plain sight across official documents for anyone willing to look closer.
For over a decade, city officials abandoned the automated Bank Reconciliation module while lumping nine bank accounts into a single ledger code, wasted approximately $1.33 million ($1,338,947.20 projected over 17 years at the 2026 rate) in maintenance fees on 24 dormant software modules that staff never used, disabled audit logging, left GL override hard-stops downgraded and wide open for abuse, coerced staff into sharing passwords, and left citywide “God Mode” administrative permissions active for a former Deputy Auditor 14 months after she transferred out of the Auditor’s office.
This sheer volume of documented control failures—spanning permissions, disabled modules, hybrid cash/accrual corruption, and off-book shadow ledgers—is precisely why Marion Watch and our investigative network have relentlessly demanded a full, independent Forensic IT Audit executed strictly in accordance with non-negotiable industry standards (NIST SP 800-86, ISO/IEC 27037, and ISACA COBIT) long before we published our evidentiary archive.
And that archive is not even finished—there is more to release if needed.
A conventional financial audit only checks the math on the page; it is not a deep investigation, and it relies on surface-level samples.
It cannot determine who disabled the digital locks, who clicked past budget hard-stops, who manipulated user permissions, or who forced unauthorized transactions through the system.
With such drastic failures now proven on the public record, it is highly probable that chargeable offenses are buried in the native data.
If an external, symptom-based diagnostic uncovered this level of systemic rot, a full forensic IT extraction will almost certainly expose a far wider array of abuses—a reality universally recognized in enterprise IT doctrine whenever a catastrophe of this scale transpires.
At Monday night’s Marion City Council Finance Committee meeting (November 16, 2026), however, the public witnessed yet another alarming display of deflection, historical revisionism, and institutional resistance to uncovering the truth.
At least the fabled 2019 “fiscal excellence” award—which we proved was little more than a cosmetic presentation trophy for financial report formatting, grossly exaggerated to mask a rotting ledger—was not trotted out again.
Perhaps once the few remaining opponents of the truth actually read the Silent Sabotage series, they will join the majority of citizens and officials who now recognize that these were severe, systemic failures deliberately masked and hidden from the public.
THE FAILSAFE: WHY THE SPECIAL INVESTIGATIVE COMMITTEE MATTERS
During the November 16 committee session, Councilman Ralph Smith confirmed on the record that a formal request has already been transmitted to the Ohio Auditor of State (AOS) seeking a forensic audit of the General Ledger, GL overrides, and system permissions dating back to 2008—the year the New World ERP contract was executed—ahead of its July 2009 go-live.
Investigating back to system installation is both consistent with and demanded by established forensic IT doctrine.
The proposed Special Investigative Committee (Finance 77) is strictly a contingency plan.
It activates only if the AOS declines, delays, or restricts the scope of a full examination into the General Ledger, GL override abuse, and system permissions from installation forward.
If enacted and called upon, Marion Watch stands ready to apply the same forensic IT doctrine demonstrated throughout our reporting to help Council target the exact logs, tables, and artifacts needed to prove what occurred inside City Hall, and if needed escalate it ourselves.
This doctrine has served as our operational “map” from day one—an enterprise blueprint we have never strayed from, proving just how accurate a disciplined, symptom-based external forensic IT assessment can be.
Since relaunching in late 2024, Marion Watch has published relentlessly, transmitting massive volumes of verified documentation over the past two years—including both a formal forensic submission to the full Council and a direct technical breakdown to Councilman Smith ahead of Monday’s meeting.
Yet despite every single warning being corroborated beyond doubt, the resolution passed out of committee on a 2–1 vote—with Finance Chairman Aaron Rollins casting the lone “No” vote and once again turning combative toward citizens and fellow council members who are reading the heavily documented receipts instead of parroting the former administration’s disproven rhetoric.
DISMANTLING COUNCILMAN ROLLINS’S SELF-CONTRADICTING “2020” MYTH
In casting his lone “No” vote, Councilman Rollins doubled down on a talking point that collapses the moment it touches the official public record—and worse, his own statements on Monday night directly proved Marion Watch’s forensic assessment.
Rollins stated on the record that his conclusion sides with the Auditor of State’s alleged view that in 2020, when the city stopped reconciling its books, it began running continuous negative line items year after year—declaring that he will not support the legislation.
Every single pillar of Rollins’s defense contradicts either the official audits or his own words:
● Rollins Accidentally Proved Our GL Override Diagnosis: By admitting on the record that Marion ran continuous negative line items year after year, Rollins inadvertently validated the exact software sabotage he voted not to investigate. In a properly configured Tier-1 ERP system with budgetary hard-stops intact, it is digitally impossible to run continuous negative line items. That can only happen when automated hard-stops are downgraded to bypassable “soft stops” and universal GL override permissions are left wide open—the exact vulnerability the City Auditor was forced to revoke on October 27, 2025.
● A Decade of Audited Negative Balances Pre-2020: Rollins told the room he had reviewed the evidence packet sent to committee members before the meeting—yet that very packet (approximately 800 pages), contains official State of Ohio audits proving Marion was hemorrhaging negative fund and cash balances a full decade before 2020. In 2010 alone—the first full year on New World—the city recorded $16,062,830 in expenditures exceeding appropriations (driven by disabled budgetary hard-stops, failed posting controls, and GL override abuses that persisted across the entire timespan), 15 deficit funds totaling $5,740,016, and 9 negative-cash funds totaling $625,916. In 2011, deficits expanded to $6,808,917 across 13 funds (including a $1,122,640 General Fund deficit) alongside 6 negative-cash funds. By 2018 and 2019, Marion’s governmental unrestricted net position had plunged to -$39,835,858 and -$28,887,649, respectively. You cannot claim to “side with the Auditor of State” while ignoring a decade of the Auditor of State’s own published audits.
● Rollins Was Personally CC’d on the “80% Unused Modules” Admission: Rollins cannot credibly pretend the financial failures began in 2020 when Mayor Collins personally copied him on the January 5, 2026 email holding the Tyler invoice—an email in which the Mayor admitted in writing that the city does not use “80% or more of the modules listed on the bill” and had been paying for them for “the past I don’t know how many years”.
● Veritas Solutions Group Confirmed Historic, Pre-2020 Reconciliation Failures: Rollins also ignores the city’s own hired consultants. Brought in after 2020 to untangle a ledger collapse triggered by undocumented, unshared manual workarounds, Veritas Solutions Group explicitly confirmed that the reconciliation breakdowns were historic and predated 2020—with “tribal knowledge” dependencies and $600,000+ in report variances tracing back into 2019 and beyond. Veritas also warned the city that these configuration failures invited theft. Crucially, Veritas Managing Director Greg Blate confirmed on January 22, 2024, that New World operated as designed—aligning with the vendor’s own testimony before Council and the 2008 New World contract itself, which placed 100% of configuration responsibility on the city. That proved the collapse was internal configuration and workflow sabotage—yet Council and the state barred Veritas from looking closer at pre-2020 balances or auditing the ever-problematic Utility Billing department.
● The Reconciliation Formatting Reality Under Landon: While the city did struggle to submit bank reconciliations in the AOS’s preferred format during former Auditor Robert Landon’s tenure, the documentary record proves why. For over a decade, the Carr administration abandoned the automated Bank Reconciliation module and relied on undocumented manual workarounds, “Shadow QuickBooks” ledgers, and hybrid cash/accrual utility configurations that only one person understood. State Auditor GAAP specialist Belinda Miller admitted on the public record on November 8, 2021, that state auditors had known about this defective hybrid setup for “10 to 12 years”. When that undocumented “tribal knowledge” walked out the door in January 2020, incoming staff under Landon inherited a crippled software system without the secret map of manual plugs needed to keep the illusion alive. That sits alongside a long list of documented anomalies—including the $1.18 million payroll tax misdirection that functioning controls would have immediately flagged, an inactive “ghost employee” injected into a live payroll batch, unexplained after-hours and weekend logins, disabled audit trails in the Magic-Wrighter ACH software, and internal “permissions wars” corroborated by native system screenshots.
Rollins argued Monday night that Marion must “move forward” without looking back to 2008 because the city’s bond rating is essential to finance emergencies like a major downtown sewer repair.
That argument destroys his own vote.
Finding the root cause and ensuring real accountability is non-negotiable—and after the scale of damage inflicted on this community, the citizens of Marion deserve to know exactly what happened.
The 2021 Single Audit (Note 20) prints the truth in black and white: Standard & Poor’s downgraded Marion from A to BBB in June 2022 and completely withdrew its bond rating in April 2023 specifically because 16 years of abandoned GAAP reporting, manual plugs, and broken controls made the city’s books unauditable.
Worse, just minutes before Rollins voted “No” in the name of moving forward, his own committee was briefed that in mid-November 2026, 2026 ADP payroll is still only entered into New World through April or May—forcing staff to enter payroll data by hand just to read the budget while the 2023 audit sits unfinished and 2024 reconciliations drag on.
Furthermore, the 24 canceled modules raise urgent, unanswered questions from every professional on our team, our broader network, and the citizenry. If the very modules whose abandonment triggered repeated state and federal audit citations have now been terminated, how is the city currently tracking capital assets, grants, requisitions, and GAAP accruals to ensure statutory compliance?
You do not restore creditworthiness—or the confidence of the citizenry—by burying the cause of the collapse while the same broken workflows continue to blindfold City Hall.
ACCOUNTABILITY IN WORDS ONLY: MAYOR COLLINS AND LAW DIRECTOR RUSSELL
Even more troubling than Rollins’s vote was the defensive posture of the senior administration.
Earlier in the crisis, in late 2025, Mayor Bill Collins—a former law enforcement official who should recognize a digital crime scene when it is laid out before him in detail—sought guidance on the council record regarding a forensic audit before abruptly reversing course.
On Monday night, Collins echoed the exact same flawed timeline as Rollins, remarking that if the administration and council only had to deal with 2024 and beyond, everything would be fine, while claiming they are simply stuck going back to 2020 to pick up where things left off.
The financial catastrophe long predates 2020. That is not an opinion—it is a proven, audited fact, and continuing to point to 2020 as the starting line is precisely why the public believes accountability is being dodged.
Law Director Mark Russell went even further, stepping in to run interference for the absent Auditor and Deputy Auditor and attempting to shut down demands for a forensic audit with a talking point that completely backfired. Russell told the committee that the Auditor of State’s office has said many times it has not observed an instance where money went somewhere it shouldn’t have or is missing—arguing that if the AOS had observed missing money, they would be here.
Russell’s defense does not exonerate City Hall—it indicts it:
● Conventional Audits Do Not Catch Digital Sabotage: Standard financial audits sample surface-level math; they do not extract native SQL databases, audit user permission tables, or inspect disabled override logs. In Dixon, Illinois, standard external audits failed to catch a $53.7 million fraud for 22 years because auditors never tested the Comptroller’s “God Mode” software permissions.
● State-Approved Audits Already Missed Active Theft in Marion: As Councilman Ralph Smith pointed out during Monday’s meeting, the State of Ohio signed off on Marion’s audits while Utility Supervisor Brenda Nwosu was actively embezzling $34,276 across 71 customer accounts between 2011 and 2014—a theft enabled by the exact disabled workflows, dormant safety modules, broken controls, and bad-debt purges Marion Watch documented.
● Unaccounted Cash and Illegal Spending Are Already Proven: Claiming the AOS hasn’t found “missing money” ignores the $543,079 unsupported bank-to-book variance in 2021, the $2.5 million cross-fund discrepancy hole, the off-book “Cashless Evidence Room” bank account that Police Chief Jay McDonald admitted “doesn’t go into New World”, and the $24.91 million in documented control exposure from illegal, unappropriated spending processed in violation of ORC § 5705.41(B)—all cited directly in official records.
When a former law enforcement officer and a city Law Director preach “accountability” in speeches while claiming the senior administration should not be “burdened by escalation” efforts—and using flawed audit definitions to block a forensic extraction of the servers—the public is right to ask why.
Former law enforcement officers, financial professionals, and enterprise IT specialists spanning multiple states who have reviewed this record are growing deeply suspicious—openly questioning why a full forensic audit has not yet begun even after formal escalation to the Ohio Auditor of State and the Special Investigations Unit opening a case.
There is more than enough evidence to justify an independent forensic IT audit by state and federal oversight agencies and law enforcement entities. Every outside expert in finance, law enforcement, and IT who has examined our archive has urged Marion Watch to transmit every single piece of data to higher authorities in light of the obvious deflection and sudden political about-face—all echoing the exact same question: “What is really going on here?”
It is time for the administration to abandon the political lore and confront reality—because the official record easily destroys the false narratives.
CITIZENS PUSH BACK: KIM MAYER AND DAMION GREENAWALT CUT THROUGH THE SPIN
When a skeptical attendee questioned who Marion Watch is—suggesting the $24 million figure pulled directly from official State audits was “unverified” and asking why Council should revisit audits the State already approved—local activist Kim Mayer (5th Ward) dismantled the deflection on the public floor.
Mayer—who is not a member of Marion Watch, though she has communicated regularly with our team and seen firsthand the depth of our investigative network—has been relentless in her pursuit of the truth. She does not come from a technical IT background, yet like the citizens and officials who have actually read the study, she grasped the published forensic record immediately—proving that the refusal by certain officials on the dais to understand the evidence is a choice, not a complexity problem.
Mayer redirected the room straight to the core issue city leadership refuses to confront, emphasizing that the crisis must be addressed on the IT side—specifically permissions and system controls—not just the financial side. Correcting the dismissive characterization of Marion Watch, she noted that the investigative network comprises experienced professionals across law enforcement, legal, IT, finance, and other fields.
She then turned directly to Councilman Rollins, asking whether he had actually reviewed the evidence submitted to the committee. When Rollins insisted he had reviewed the data—a claim directly contradicted by his refusal to acknowledge the 2009–2019 State Audits printed inside that very packet—and declared his stance unchanged, Mayer delivered a blunt verdict to the entire chamber: the information provided to Council and the administration is overwhelming, and anyone who has seen it and still disagrees that a forensic investigation is necessary should consider resigning. Rollins’s response was to cut her off and order her to sit down.
Mayer’s demand is increasingly echoed across thousands of comments and posts on social media, private messages, and direct communications from residents and sources watching this circus of denial unfold.
Later in the meeting, resident Damion Greenawalt called out the utter lack of accountability from an Auditor’s office whose leadership did not even attend the Finance Committee to defend their own appropriations—stating that paying officials who aren’t there to answer questions is wasted money. While the senior administration explained that the absences were prearranged, the frustration in the room was unmistakable.
Mayer then returned to the microphone to voice the exact question echoing across Marion: since the problem started long before the current Auditor arrived—and before the last two resigned—why won’t officials dig in and get answers? When citizens don’t see leaders making the effort to investigate, she warned, it makes the public wonder if they are covering something up—or hiding something for somebody else.
THE TIMELINE DOESN’T LIE: HOW MARION WATCH FORCED THE TRUTH INTO THE LIGHT
For anyone still questioning the credibility or accuracy of Marion Watch Investigates, our work—built almost entirely on state audits and official municipal records—was formally evaluated by a multi-state network of enterprise IT, financial, and retired law enforcement professionals and graded at 98% (A+) overall forensic accuracy and 100% (A+) accuracy on module and misconfiguration diagnosis. The final two points were reserved solely because the city continues to withhold native IT logs and permission matrices.
The documented paper trail proves that Marion Watch did not drop “unverified” claims on Council’s desk—our symptom-based IT diagnostics predicted and forced every major revelation into the open:
● Early March 2025 (The Initial Diagnosis): Marion Watch met with Councilman Ralph Smith, presenting our symptom-based forensic diagnosis of New World ERP—specifically flagging GL override abuse, dormant modules, shared passwords, and unimpeded administrative access based on pre-2020 audit research.
● July 21–25, 2025 (Council Floor Address & SIU Escalation): Marion Watch formally addressed City Council on the public record regarding disabled safety switches and coerced password sharing, then submitted a formal forensic threat assessment to the Ohio Auditor of State Special Investigations Unit (SIU).
● September 25–29, 2025 (Special Audit Task Force & “God Mode” Proof): After the SIU forwarded our complaint to the Special Audit Task Force, Marion Watch submitted native system data proving former Deputy Auditor Cathy Chaffin retained citywide “God Mode” administrative access in the New World ERP system 14 months after leaving the Auditor’s office, alongside server room security breaches and additional archival records.
● October 15 – November 13, 2025 (The 2021 Audit Detonation & Override Lockdown): The State Auditor issued 11 Qualified Opinions across 14 opinion units and stripped Marion of its illegal five-year Low-Risk Auditee status. On October 27, 2025—more than six months after our warning to Council—the City Auditor finally revoked universal GL override permissions from all users except the Auditor.
● December 14–15, 2025 (The Public Records Catalyst): At 6:13 PM on December 14, Marion Watch filed a public records request with Mayor Collins and Treasurer Twila Laing for the Original Purchase Manifest, User Permissions List, and Tyler Help Desk Logs to investigate unused modules. Less than 19 hours later, Mayor Collins emailed the Auditor’s office asking what the city was paying for New World.
● January 5, 2026 (The 80% Confession): Following an internal review triggered by our records request, Mayor Collins ordered payment held on the 2026 Tyler invoice—CC’ing Councilman Aaron Rollins—admitting in writing: “I found that we do not use 80% or more of the modules listed on the bill”. Collins also noted in internal correspondence that several billed modules may never have been used—a reality subsequently proven by the city’s formal cancellation of 24 unused applications.
● July 6 – August 17, 2026 (The Cover-Up & The 24-Module Cancellation): While IT Supervisor Jacob Boldin issued an unlawful blanket denial claiming user accounts and permissions “are not public record”, the city quietly executed Tyler Technologies’ Discontinuance Acknowledgement canceling 24 dormant applications—checking the reason box “Don’t use” and confirming approximately $1.33 million in wasted maintenance.
THE VERDICT
You cannot migrate 16 years of corrupted ledgers, phantom utility revenue, and unverified manual plugs into a new software platform without sanitizing the data—that is textbook garbage in, garbage out. No competent information technology professional would certify this data; doing so would be professional negligence.
Worse, decommissioning legacy New World servers without a court-ordered preservation directive risks destroying what carries a 95% to 99% probability of containing evidence of chargeable state and federal offenses (possibly including ORC § 2913.42 Tampering with Records and ORC § 2913.04 Unauthorized Computer Use).
Marion City Council must enact an immediate preservation directive, pass the Special Investigative Committee failsafe, and compel the release of every withheld permission matrix and vendor CRM log.
Marion Watch chose to work cooperatively with City of Marion officials to get this escalated properly. However, it has now been nearly two years since we first brought these failures to city leadership. If the games continue and local and state authorities keep obstructing a conflict-screened, wall-to-wall Forensic IT Audit, Marion Watch is prepared to escalate our complete evidentiary archive directly to federal oversight authorities outside the State of Ohio—including the FBI Computer Analysis Response Team (CART), the Office of the Inspector General, and the U.S. Department of Justice.
The timeline does not lie.
The audits do not lie.
The citizens of Marion deserve the truth, and accountability in words only will no longer be tolerated.